Propane Supply & Pricing Outlook for 2026-27
Supply experts discuss the effects of global conflict, exports, tariffs & more on planning for the next heating season
As the winter of 2025-26 goes into the books, propane retailers are now turning their attention to propane supply planning for winter 2026-27. This past winter was notable for some decent periods of extreme cold and strong production, but also high levels of export capacity and good profit margins for retailers.
In February, BPN spoke with several supply experts regarding issues ahead of winter 2026-27. It is important to note these thoughts were provided before United States airstrikes in Iran on Feb. 28. On Feb. 27, crude oil was trading around $66 per barrel; Mont Belvieu, Texas, propane was at 66 cents per gallon (cpg); and Conway, Kansas, propane was at 60 cpg.
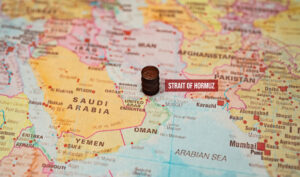
The airstrikes in Iran and the immediate fallout changed the dynamics, as major world events often do. As time goes on, though, sometimes supply disruptions are resolved quickly and a price spike one day ends up followed by a decline that is sometimes as fast as the spike. Our experts discussed looming tensions between the U.S. and Iran before they became a reality. As our article goes to press on March 18, we simply don’t know the answer to key questions that will be playing out for the next several weeks and months — some before and some after you read this article. By now, we do know that crude oil shipments have been severely slowed at the Strait of Hormuz, which usually sees 20% of the world’s crude supply flow through each year. Our current challenges would be more severe if they occured during the last major U.S. conflict with Iran in 1979, when the U.S. produced far less crude oil, natural gas and propane.
A fairly quick end to hostilities may move the markets back closer to the Feb. 27 prices. As the week ended on March 13, crude averaged $94 after having bounced above $100 several times during the week. Indeed, as some of our experts thought may happen if U.S. military action erupted in Iran, Mont Belvieu propane was trading at a lower percentage to crude oil at 34% on March 13, down from the 42% level on Feb. 27, with Mont Belvieu propane at 77 cpg and Conway propane at 69 cpg.
Aside from the beginning of the Russian-Ukraine war, which just entered its fifth year in February, crude oil prices have remained in the $55 to $75 range during the war until the aftermath of the U.S. airstrikes on Iran on Feb. 28. If key supply distribution issues are resolved soon, we may ultimately see prices back in this range in the coming weeks or months. With that in mind, the rest of the article shares our experts’ thoughts prior to the Feb. 28 airstrikes in Iran.
With Global Tensions Rising, How Could 2026-27 Supply Planning Be Affected?
“I think retailers must look at the supply world from the perspective of how prices will move higher,” said Jeff Thompson, propane consultant at Propane Resources. “This is not because I want prices to move higher. Simply, the risk of $1.50 propane is greater than 30-cent propane. The market could see 30-cent propane, but it will not last if we do see it.”
Thompson feels the risk is a world where propane prices are based on crude oil price curves with some percentage flexibility with propane pricing. “As an example, if WTI crude moves to $45 a barrel, propane can change its percentage to crude to 55%, putting spot pricing at 58 cents a gallon,” he said, “Let’s say Iran and the U.S. get into a hot war. If crude goes to $80 a barrel, propane could slip to 35% of crude or less for a period (especially coming out of heating season with high inventory levels).”
Thompson believed propane on a spot basis could price at 65 to 66 cpg. “What these scenarios paint is limited downside to the propane market from current price levels. It is hard to think of strong upside drivers right now in the market, as well, but I am looking for reasons this market moves up, not down.”
“Consider the risk associated with geopolitical conflicts today as a reality, not as a possibility,” said Phil Farris, director of wholesale marketing at 3Eight Energy. “The continuing conflict between Russia and Ukraine, tensions in the Middle East and the brewing disruptions in Africa all affect demand for U.S. exports. While the U.S. is a major producer, propane is a global commodity, and the U.S. NGL market can get swept up with energy markets in the event of a disruption.”
Farris said marketers have no control over the events or the reactions, but they can control your exposure and the potential impact of such events on your business. “Take the time to prepare and protect yourself financially by always having a fixed price supply option or backstop in place. That kind of supply cost protection is not just for homegrown winter issues.”
“The ongoing volatility in the international political environment will likely pose risks to price, not supply volumes, for the domestic business,” said Anne Keller, managing director of Midstream Energy Group. “The U.S. market is so long propane, at least on the Gulf Coast, that it shouldn’t be difficult to replenish inventories that have been pulled way down by this crazy winter. The issue is deciding what price you’re willing to lock in for and whether you want to top up storage.”
Going forward, Keller would ask the data center industry whether it’s willing to take chances on price and the availability of gas for all the power it wants to add, given the expansion in export capacity and potential for slowing production growth. “Propane could be a good alternative idea for powering these facilities.”
DD Alexander, president of Global Gas and chair-elect of the National Propane Gas Association, commented that crude oil has been projected to be over-supplied throughout 2026 and beyond. “If Russia and Ukraine remain at war, there is the potential for more of Russia’s energy infrastructure to be destroyed and the U.S. sanctions to take hold regarding the amount of Russian oil that makes it to the market. This obviously affects the price of crude, which has a direct effect on the price of propane. If prices remain low, this is a potential opportunity for dealers to lock in historically low prices for the upcoming winter season.”
Increased Production & Export Capacity
With propane production recently increasing in the United States, but export capacity up from 1.8 million barrels per day (MMbbld) to 2.4 MMbbld, what are the challenges to maintaining strong supply levels in the U.S.?
“Price is a strong neutralizer,” said Alexander. “Currently, inventory levels are above the five-year average and prices are below the last 10 years. If prices increase, production will grow accordingly. If there is further price erosion, exports will likely … increase.”
Alexander noted that with production where it is, the country is in the driver’s seat. “If the U.S. needs more inventory, an increase in price will most likely balance out our supply and demand.”
Thompson said he is not too concerned about maintaining strong supply levels in the U.S. “Enterprise, Targa, P66, Energy Transfer and others have not spent billions of dollars on buildouts and upgrades to not fully utilize and monetize their export facilities,” he said. “This tells me that producers and midstream companies currently are more than comfortable with the current and projected production schedules for the near future.”
Thompson believes it is reasonable to think by 2028/2029, the U.S. could have more than 3 million barrels of export capacity. “This is not built to be idle nor built to chase higher prices,” he said. “Supply should not be an issue, and an immediate concern coming out of heating season is there may be a physical issue of too much supply in the system. Of course, the greatest way to ensure supply is price.”
Keller said, “It looks like supply will still grow in 2026 due to expanding pipeline capacity out of Permian that will relieve takeaway constraints and let more gas flow through the system into the Texas Gulf Coast.”
Keller believes with oil production in the Permian Basin seemingly plateaued for now, at least, we should be set for a long time for global market access.
“Going forward, though, we’ll need to somehow resolve the issue of increasing water handling requirements to maintain drilling activity in the associated gas fields of West Texas, as well as the cost pressures that lower crude prices bring, to see significant supply growth post-2027,” she said. “Higher levels of drilling activity in Haynesville to boost LNG feed gas supply won’t bring on a lot of NGLs since a lot of these wells are deeper and ‘drier’ in the sense of having lower NGL content.”
Are Tariffs Still a Concern Amid 2026-27 Planning?
With tariffs having been a hot topic during President Donald Trump’s second term, BPN asked what challenges and concerns lie ahead due to tariff activity.
“Tariffs are an interesting topic,” Thompson said. “Prior to income taxes in the 20th century, tariffs were the primary way nations funded government operations. So, the implementation is not new or unique. The challenge becomes overseas producers paying to sell their goods and services in the U.S. and who pays the price.”
Thompson said that, from a propane point of view, nations that export goods and services look at tariffs as punitive, while nations that are net importers of goods and services look at tariffs as a reasonable and sound business practice.
“Asia — China in particular — has a structural dependency on U.S. propane,” Thompson said. “China’s PDH market is built on cheap propane. China is doing what it can to diversify, importing from Canada and the Middle East. In the end, price will be the driver. Arbitrage will always be a driver. Add in strategic trade conversations, and it is hard to see significant changes to propane export trade routes in the future.”
“The cost of keeping up with what’s become a fast-moving target increases administrative expense for government affairs, regulatory tracking and cost estimating,” Keller said. “The uncertainty due to the Supreme Court decision [to strike down President Trump’s tariffs] presents further challenges for companies trying to plan long-term capital projects, since we won’t be able to produce everything we need for them here for quite some time.”
“Fortunately, propane is exempt from tariffs on propane from Canada,” Alexander said. “We should not see tariffs as a driver for propane not being exported from Canada to the U.S.”
Alexander sees the larger factor on less gas coming to the U.S. from Canada as Canada’s increased maritime export capacity. “The Canadians are exporting a significant amount of production out of maritime ports on the western side of Canada. This is reducing the amount of propane that is available to be exported to the U.S.”
Have Allocation Challenges Become a Bigger Issue?
BPN noted retailers have expressed frustration about allocation and asked what they can do to mitigate such issues.
“I believe many in our industry got complacent during the last three years (prior to last winter) of warm winters,” Alexander said. “This led many to reduce their contracts or worse, not contract at all. It is imperative to have annual supply contracts to cover most of your winter demand. It is just as important to ensure your supply is diversified from multiple supply points.”
Alexander noted just as important is the transportation of the gas.“Make sure your supplier has a strong transportation company behind them. Having one without the other gets you nowhere!”
Keller commented that it’s possible the continued shift from producers marketing or controlling the marketing of their own propane production to having midstream companies take over that role and serving as aggregators for the export market will change the landscape for the domestic industry.
“As supply growth slows and export capacity expands, domestic companies will increasingly be in competition with buyers overseas for gallons,” she said. “In the midcontinent, Y-grade pipeline capacity continues to expand, siphoning more gallons down through Conway and on to the Gulf Coast to generate fees for midstream companies. You need to know where your supplier gets their product. And realize you may need to be open to storing more than you used to in order to have it when you need it near your markets.”
Keller said there is at least one project underway in the Permian to put in local fractionation to extract propane to ship to California in the wake of refinery closures.
“There is plenty of propane,” Thompson said. “It was in the wrong place for many retailers. Allocation is always the struggle when it’s on. Why is supply always curtailed when a retailer needs it the most?”
He said one of the best things a retailer can do is deep dive into their supply plan, post-heating season. “Retailers have a choice to build the cheapest supply plan possible and recognize there will be periods of time when supply will be nonexistent and/or expensive, or build a supply plan that is not the cheapest but keeps the retailer out of the game of picking up pennies to lose dollars.”
Thompson said that for all the allocation nightmares he heard this year, he also heard retailers with suppliers that took care of them without raising cost of goods sold excessively higher. “All it takes is one year paying 30-40 cents per gallon higher to give back and more, the 2 cents per year a retailer saved over the past 10 years. Allocation is inevitable, but if a retailer works with suppliers year-round, the suppliers will work with the retailer.”
Thompson’s advice to marketers: “First, build a marketing plan. Second, build a supply plan to fit the marketing plan. Once a retailer knows what gross margin is needed, supply becomes fairly simple. A robust supply plan is going to cost a retailer a few more cents per gallon initially to set up.”
He said this year, the setup was worth it. “The marketing plan is the driver. The more a retailer can get the customer base on budget pay and similar programs, the delivery efficiency goes up. A retailer that has the capacity and willingness to build and educate customers to take gallons in summer increases available allocated gallons in the winter. Market year-round service and delivery backed with a robust supply plan, and allocation becomes less of an issue.”
“There is no uncertainty if you are not getting the product you want or need — just stress and aggravation,” Farris said. “That’s what allocation is all about: Demand exceeds supply, so the supply is rationed out to parties. The definition itself means it will usually come at the most critical time for supply to not be disrupted or constrained. It’s not a lack of product; it is a lack of immediate delivery capacity, often when you need product most (peak cold snaps). “
Unfortunately, the rules of the game haven’t really changed,” he continued. “You can buy and sell more to earn more, but really there’s not much you can do to change the process. Downstream infrastructure has not kept pace with production or peak retail demand. While there is plenty of propane, distribution is the bottleneck. Managing propane allocation is usually a very tedious process, and its effectiveness is subject to trucking, weather and facility operational issues.
“If you think allocation is a given, you either plan to allocate your own operation (get by with what you get), or you plan on incremental supply — or both!” Farris concluded. “If you expect your supplier to simply ‘find more’ during a crisis, that isn’t a plan. Working as a team to secure alternatives is. More bulk storage can help to weather the allocation and secondary supply. This is not a ‘backup’ that you call on when desperate; it is a secondary source you commit to.”
Does It Make Sense to Buy for the Next Season or Two?
“The market is currently showing Q4 2026 prices at 45% of WTI — that seems like a decent buy,” Keller said. “My personal bias is for stronger prices in the fourth quarter; even though the Trump administration will work hard to keep crude prices down to counter concerns around affordability going into the midterm elections, I think the ‘Big Supply Surprise’ (as in, there’s not as much crude production capacity out there as we thought) will put a bid under the market by then.”
Keller said that if she were in a region that’s seeing reduced length due to refinery closures or addition of more ways to move gas plant NGLs to the coast, she would look at storage at least for 2027 and beyond.
“With the prices of propane below the 10-year pricing, there is definitely an opportunity to lock in pricing for next year for at least part of your supply needs,” Alexander said. “If we have an uptick in exports, our supply and therefore price can change in a hurry. Of course, there is always the reverse of that: If oil prices tank, propane prices will reduce further. You must look at the risk/reward and determine what is best for your operations.”
“I am watching the market to see if we get one more leg down in pricing before starting,” Thompson said. “Yet, it depends on the retailer marketing plan. There is a level of uncertainty in the market right now. If economic conditions worsen, we could see a softer propane market through the remainder of 2026. If gas prices remain lower this summer, we could see economic stability and growth, which could see crude prices push moderately higher as we head into the second half of the year. I go back to building the marketing plan first, then supply becomes a lot simpler.”
“It is a good opportunity, and if you need some evidence, look at the past 20 years,” Farris said. “Except for two relatively short periods, one being the COVID-19 experience, Mont Belvieu generally has a floor around 60 cpg. The forward market data reflects a Mont Belvieu range of 60-70 cpg. If you can secure supply at that basis range for the next two winters, you are buying near the bottom of the historical 20-year range.
“Those figures obviously equate to a higher price at the final supply point,” Farris added. “As we have seen again this winter, the Mont Belvieu basis and the terminal rack price are two separate markets. Downstream markets can quickly spike due to infrastructure and transportation limitations, allocation, weather, rail delays, etc. There is a bearish sentiment now because of over-production fears, but at 60-65 cents, the downside risk feels lower than the upside.”
Are There New Rules of Thumb Regarding Storage?
Though storage needs may vary between regions, BPN asked for any rules of thumb regarding necessary propane storage on hand for a propane company.
“Obviously, the farther away from a major hub, the more storage you should have,” Alexander said. “Storage has been harder and harder to add to retail propane plants over the last 40 years. If you have the opportunity to add storage at your facility, you should. Storage will just keep getting more valuable.”
Alexander said as far as storage owned by a third party, you still have to truck it to your facility. “Having your own storage on-site gives you maximum flexibility.”
“I looked at storage this winter,” Thompson said. “It is a tough call whether to add storage. In a perfect world, a retailer should consider the peak demand period historically and have at least three weeks of storage.
“It is possible to potentially get a similar amount of storage at similar or less cost where it is needed most at the customer’s location. This feeds back into the marketing plan and filling the customer tanks in the summer. The retailer doubles the capacity to deliver in the summer, increasing allocation availability in the winter, reducing the strain on storage limitations at the bulk facility during historically peak demand.”
“I think the only standard or rule of thumb in the Southeast is ‘more,’” Farris said. “A lot depends on proximity to supply points, transportation options and winter-to-summer ratio. The further you are from your primary supply point, the more you may need. And if you don’t have access to secondary supply, your bulk storage is even more critical.
“Propane supply infrastructure and transportation in the Southeast operates much like it has for decades,” Farris continued. “Gallons over the past two winters are up, ratios are down and the burden of storage is on the retailer. Don’t rely on the system; invest in your business and take care of yourself to manage whatever issues the winter brings. The fact that little has changed over the years puts more emphasis on relationships. Partner with experienced suppliers that are committed to your success. The retailer, the supplier and the transporter must work together as a team. Some teams are more committed and experienced than others.”
“Seems like at least once a decade someone commissions a study about storage, usually when a brutal winter has caught people short,” Keller said. “The findings haven’t changed much: Basically, the folks at the level between the pipeline terminals and the end users really don’t want to carry inventory. Level billing, off-season fills, you name it — the industry has done it to manage this significant piece of its cost.
“People who are in this business know — or can go back to see — which regions end up challenged in terms of meeting their market needs most often,” Keller added. “If you’re asking the question, you already know the answer.”
OUR DIGITAL PARTNERS